Use this guide to choose beginner-friendly financial planning books that match your needs, then turn the advice into a short list of actions. It is for readers who are new to budgeting, saving, debt repayment, investing, or retirement planning. Allow about one to two hours to compare books and set up a reading plan; reading them will take longer.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included

Personal Finance For Dummies
- ✔ ASIN: 1394207549
- ✔ Subject: Personal finance
- ✔ Stated audience: Not specified
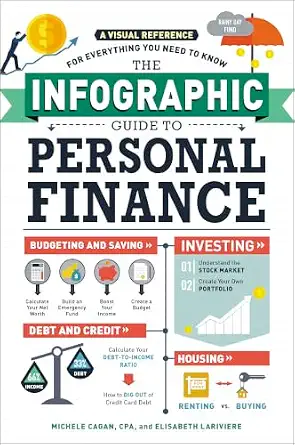
The Infographic Guide to Personal Finance: A Visual Reference for Everything You Need to Know
- ✔ ASIN: 1507204663
- ✔ Subtitle: A Visual Reference for Everything You Need to Know
- ✔ Series: Infographic Guide Series

Financial Literacy for Young Adults Simplified
- ✔ ASIN: B0C9SHJZS9
- ✔ Stated audience: Young adults
- ✔ Subject: Financial literacy
Difficulty: Beginner | Time: 1-2 hours to choose and plan; several weeks to read
What You’ll Need
Tools & Materials:
- A notes app or notebook
- Access to a library, bookstore, or ebook catalog
- A rough list of your financial goals and questions
Knowledge:
- No finance background is required
- Be ready to identify the money topic you want to work on first
You do not need to share account numbers, passwords, or other sensitive information with a book, website, or adviser to follow this guide. Books offer general education; advice about taxes, investments, debt, or benefits may depend on where you live and your circumstances.
Personal Finance For Dummies
For beginners who want one general starting point, Personal Finance For Dummies takes the top spot because its stated subject is personal finance without a narrower age or format constraint. That makes it the most flexible choice in this lineup for readers who are still figuring out which money questions matter most. Compared with Financial Literacy for Young Adults Simplified, it is not explicitly framed for a particular life stage; compared with The Infographic Guide, its description does not signal a visual-reference format.That broad positioning is also the central uncertainty. The supplied information does not name chapters, planning exercises, or the balance between saving, debt, and investing. We should not assume it provides a step-by-step financial plan just because it is a personal finance book. It makes the most sense when we want a general introduction and are comfortable checking the contents first. Readers who learn best through graphics may prefer the infographic title, while younger readers seeking a guide addressed to their stage of life may find the third pick more personally relevant.
Pros:
- Broad personal finance positioning can suit beginners with varied starting questions.
- Does not signal a narrow age-specific audience in the supplied description.
- Offers a straightforward candidate for readers comparing general introductory books.
- May be a practical first shortlist choice when format is not the deciding factor.
Cons:
- The available description does not specify topics, depth, or learning aids.
- We cannot confirm whether it includes actionable planning steps or exercises.
- Its broad framing may feel less tailored than the young-adult-focused alternative.
Best for: Beginners seeking a general personal finance starting point without a stated age-specific focus.
Not ideal for: Readers who need a confirmed topic-by-topic planning program, a visual-first format, or guidance explicitly tailored to young adults.
Bottom line: We rank it first as the most flexible general-purpose entry point, provided its contents match the beginner topics we want to learn.
“We rank it first as the most flexible general-purpose entry point, provided its contents match the beginner topics we want to learn.”
The Infographic Guide to Personal Finance: A Visual Reference for Everything You Need to Know
The Infographic Guide to Personal Finance is the clearest format-led choice here. Its title presents it as a visual reference, which gives readers a reason to consider it if diagrams and at-a-glance explanations feel more approachable than a text-heavy introduction. That role separates it from Personal Finance For Dummies, whose supplied description gives no comparable format cue. The series name, Infographic Guide Series, reinforces that visual-reference positioning.For a beginner, visual presentation can make an unfamiliar subject feel easier to browse, but it does not tell us how thoroughly each topic is explained. The provided details do not identify specific subjects, examples, or planning tools, so we cannot confirm that the book covers the decisions a reader needs help with. It ranks second because the format is distinctive but the scope is less clearly described than the young-adult book’s stated focus on money management, saving, and investing. Choose it when visual navigation is a priority; skip it if we need a confirmed, detailed sequence for building a financial plan.
Pros:
- Its title clearly signals a visual-reference approach.
- The infographic format may help readers scan concepts and find topics quickly.
- It offers a distinct alternative to the broadly framed Personal Finance For Dummies.
- The series identity supports its positioning as a reference-style guide.
Cons:
- The supplied description does not list the specific personal finance topics included.
- We cannot establish how much explanation accompanies the visual material.
- No details confirm exercises, planning templates, or a step-by-step sequence.
Best for: Beginners who prefer a visual reference and want to browse personal finance concepts in infographic form.
Not ideal for: Readers who need confirmed coverage of particular planning topics or prefer a detailed text-led progression.
Bottom line: We recommend it when visual presentation is the deciding factor, while advising beginners to verify the contents for their specific planning needs.
“We recommend it when visual presentation is the deciding factor, while advising beginners to verify the contents for their specific planning needs.”
Financial Literacy for Young Adults Simplified
Among these three, Financial Literacy for Young Adults Simplified has the most explicit audience and subject outline. It is described as a guide for young adults covering money management, saving, and investing, with the aim of helping readers build a secure and independent financial future. That gives a younger beginner a clearer reason to choose it than either general personal finance title. In particular, its stated topics are more concrete than the descriptions supplied for Personal Finance For Dummies and the infographic guide.Its audience focus is also a limit. Readers outside that life stage may prefer the more general framing of the top-ranked title, and the description does not explain how the three stated areas are handled or whether other planning subjects are included. We have no supplied details about exercises, examples, or depth, so the word “simplified” should not be treated as proof of a complete program. It ranks third overall because its fit is excellent for a specific reader but narrower than the broad first pick. For young adults choosing a first book, however, it may be the most directly relevant option.
Pros:
- Explicitly written for young adults.
- The description identifies money management, saving, and investing.
- Its stated aim connects financial learning with independence and security.
- Its audience focus makes it easier to assess fit than the less-detailed alternatives.
Cons:
- The supplied details do not explain the depth of coverage for each stated subject.
- No information confirms whether it includes budgeting tools, exercises, or a structured plan.
- The young-adult focus may be less relevant to readers seeking age-neutral guidance.
Best for: Young adults who want an introductory guide with stated coverage of money management, saving, and investing.
Not ideal for: Readers looking for an age-neutral reference or confirmed, detailed guidance on a particular financial planning topic.
Bottom line: For young adults, its stated audience and topic list make it a focused beginner option; other readers may get a better fit from the broader first pick.
“For young adults, its stated audience and topic list make it a focused beginner option; other readers may get a better fit from the broader first pick.”
As an Amazon Associate we earn from qualifying purchases.
Before You Start
Write down the country or region whose financial system applies to you. Rules for taxes, retirement accounts, insurance, and investing differ. If a book assumes US-specific accounts or laws, check whether its advice applies where you live before acting on it.
Set a modest reading goal, such as one chapter a week. You do not need to buy several books at once: borrow a copy or read a sample first, and choose the next title after you know what questions remain.
Step-by-Step Instructions
Step 1: Choose your first money question
Write one sentence naming the task you want help with. Make it specific, such as “I want to track spending and build a monthly budget,” “I need a plan to pay down high-interest debt,” or “I want to understand diversified investing.” If you have several concerns, list them and mark the one that would make the biggest difference over the next three months.
Use the same question to judge every book. A title that covers all of personal finance may be useful later, but a focused guide can be easier to apply when you are starting out.
Tip:If you are facing an urgent issue, such as a missed housing payment or a debt collection notice, look for qualified local help as well as a book. A book may not address deadlines or rules that apply to your situation.
Check: You have one clear topic to search for and can explain why it matters now.
Step 2: Set a budget and reading format
Decide how much you are willing to spend, including whether the right price is zero. Search your public library’s print, ebook, and audiobook catalog before buying. If you plan to read on a phone or listen while commuting, choose a format you can use consistently; check that tables, worksheets, or charts remain accessible in that format.
Borrowing is a good way to inspect a book before paying. If a copy is unavailable, place a hold or search for a sample chapter from a legitimate source rather than relying on an excerpt that omits the book’s context.
Check: You know your spending limit and where you can preview or borrow candidate books.
Step 3: Find a short list of candidates
Search for beginner personal finance books using your chosen topic and the country or region that applies to you. Check library catalogs, reputable booksellers, and reading lists from established nonprofits or educators. Add no more than five titles to your shortlist so comparison stays manageable.
Look for books that explain basic terms, show practical examples, and provide a method you can follow. A budgeting title should explain how to track income and expenses; a debt guide should describe how to compare balances, interest rates, and payment approaches; an investing book should explain risk, diversification, and fees in plain language.
Tip:Ratings can help you find candidates, but they do not show whether a book fits your goals, location, or experience level. Read a sample or inspect the contents page.
Check: Your shortlist contains books on your chosen topic, with at least one you can preview.
Step 4: Check the book’s fit and reliability
Review each candidate’s publication date, author background, contents, and sample pages. Prefer clear explanations over promises of quick wealth or guaranteed results. Check whether the author distinguishes general education from individualized advice and whether the book explains risks and tradeoffs.
Look for location-specific assumptions. A book may use tax rules, pension systems, account types, or consumer protections that do not apply where you live. If those details are central to the topic, choose a locally relevant guide or pair the book with information from an official regulator or government agency.
Set aside books that rely on pressure to buy a course, a particular investment, or a financial product. A useful beginner guide should help you understand choices, not make a sales pitch feel like the only answer.
Tip:A recent date matters most when the advice depends on changing laws, account limits, rates, or products. Foundational ideas may remain useful, but verify time-sensitive details.
Check: You can explain why your preferred title fits your goal, your level, and your location.
Step 5: Choose one starting book
Select the candidate with the clearest path to your current goal. Read its introduction and first chapter before deciding to continue. Notice whether you understand the examples and whether the author defines unfamiliar terms. If you have to stop repeatedly to decode jargon, try another beginner title.
Choose one main book rather than starting several at once. If a book has worksheets, check that they ask for information you can gather without exposing private data. Keep only the notes that help you make decisions; do not record account credentials or full financial identifiers.
Check: You have one book you can access and a clear reason for reading it.
Step 6: Read with a practical note system
Set aside a regular reading slot, such as twenty minutes twice a week, and read one chapter at a time. After each chapter, write three brief notes: the main idea, one question you still have, and one action you could take. Mark advice that depends on local rules or your personal circumstances so you can verify it before acting.
Separate the author’s general principles from examples based on a particular income, family, tax system, or investment account. Treat sample budgets and projections as illustrations rather than targets you must match. If you disagree with an approach or it does not suit your constraints, record why instead of forcing it.
Tip:Use a small notebook or private notes app. A reading log should make the next action clear without becoming a record of sensitive financial details.
Check: Your notes include useful ideas and open questions, not just copied passages.
Step 7: Turn one idea into a safe action
Choose one action that is within your control and matches the book’s topic. Examples include recording expenses for a week, listing debt balances and interest rates, setting a savings goal, or learning the fees on an investment account. Start with information gathering or a small reversible change before making a large financial commitment.
Before changing investments, taking out a loan, moving retirement savings, or making a tax decision, verify the relevant rules and costs with an official source or qualified professional. Do not act on a book’s example as though it were tailored to your finances. Write down what you will do, when you will do it, and what result you expect to see.
Tip:Keep the first action small enough to complete in a week. Finishing one useful step is more valuable than building a long plan you cannot maintain.
Check: You have one dated action and a way to tell whether you completed it.
Step 8: Review and select the next resource
After finishing the book or reaching its relevant chapters, review your notes. Mark which ideas you used, which questions remain, and whether the book addressed your original goal. If you need another resource, choose one that fills a specific gap, such as local tax basics or a deeper explanation of retirement saving.
Compare the next resource using the same checks for level, location, publication date, clarity, and sales claims. If the book did not help, stop reading it and try a better fit; finishing every book is not necessary.
Check: You can name what you learned, what you still need to know, and the next concrete step.
Common Mistakes to Avoid
- Buying several popular books before checking whether they fit your location or goal. — Choose one topic first, preview a candidate, and borrow it when possible.
- Treating an author’s personal story or sample plan as a rule for everyone. — Separate examples from general principles and check whether your circumstances match the example.
- Trying to change your budget, debt payments, and investments all at once. — Choose one small action, complete it, then decide what to change next.
- Following time-sensitive tax or investment details from an old edition without checking them. — Verify current rules with an official local source before making decisions that depend on them.
Troubleshooting
Problem: The book uses terms you do not understand.
Solution: Pause and look up the term in a reputable financial education glossary or official source. If jargon continues to block you, switch to a more introductory title.
Problem: The advice refers to accounts or laws from another country.
Solution: Do not copy those instructions directly. Find a local guide or confirm the equivalent rules with a government agency, regulator, or qualified professional.
Problem: The book feels too broad and you are not making progress.
Solution: Return to your one-sentence goal. Read only the chapters related to it, or choose a focused book with examples for that task.
Problem: You cannot afford the book or it is unavailable.
Solution: Check library print and digital catalogs, request an interlibrary loan, or use free educational material from a reputable nonprofit or public agency.
What Success Looks Like
You have selected a beginner-friendly book that matches a specific financial goal and the rules where you live. You can explain its main ideas in your own words, have recorded any questions that need checking, and have completed or scheduled one small action. You know what result to look for and where to verify advice that depends on current laws, products, or personal circumstances.
Next Steps
Review your chosen action after a week or month and note what changed. Keep the parts of the plan that work, adjust the parts that do not, and choose another book only when a clear question remains. For complex tax, debt, investment, or retirement decisions, use locally qualified help and bring your questions and notes. Recheck time-sensitive details before acting on them again.
Frequently Asked Questions
Should I buy a financial planning book or borrow one?
Borrow or preview it if you are unsure about the author’s style or the book’s fit. Buy a copy if you want to keep worksheets or return to a reference you expect to use. Check the library’s ebook and audiobook options as well as print holdings.
How can I tell whether a finance book is suitable for beginners?
Read a sample chapter and check whether it defines basic terms, explains examples step by step, and acknowledges risk and tradeoffs. If the text assumes detailed investment or tax knowledge without explanation, choose a more introductory title.
How many books should I read before making a plan?
One relevant book can help you make a simple first plan. Use a second source to check claims or answer a specific remaining question. You do not need to read a long list before tracking spending or setting a modest savings goal.
Can a book tell me exactly which investments to buy?
A general book cannot account for your full financial situation, risk tolerance, taxes, or local rules. Use it to learn concepts such as diversification, fees, and risk, then verify choices with reliable local sources or a qualified professional.
What should I do if a book’s advice conflicts with another source?
Check the publication dates, the country each source covers, and whether the recommendation depends on your personal circumstances. For legal, tax, or regulated financial matters, favor current official guidance and ask a qualified local professional when the answer affects a major decision.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.